Use this resourceTools
- Purpose
- Connect contribution review, agreed rights, and actual fulfillment. Use the same review date to check which conditions are met, which obligations are due, and how much the evidence supports as fulfilled.
- Conditions for use
- Check that the subject, objective and constraints fit the task. Confirm any conditions that the article does not specify.
- Tools
- Fields, records and interpretation rules
- Evidence and validation limits
- Editable Excel tool V0.1. The workbook is in Chinese. The channel partnership and amounts are fictional. No separate external-validation result is recorded for this article. Publication does not establish effectiveness; check the evidence, assumptions and limits in the text.
- Version
- V0.1 · Revised 2026-11-14
- Original diagrams and files
- Download the editable Excel tracking sheet (Chinese) ↓
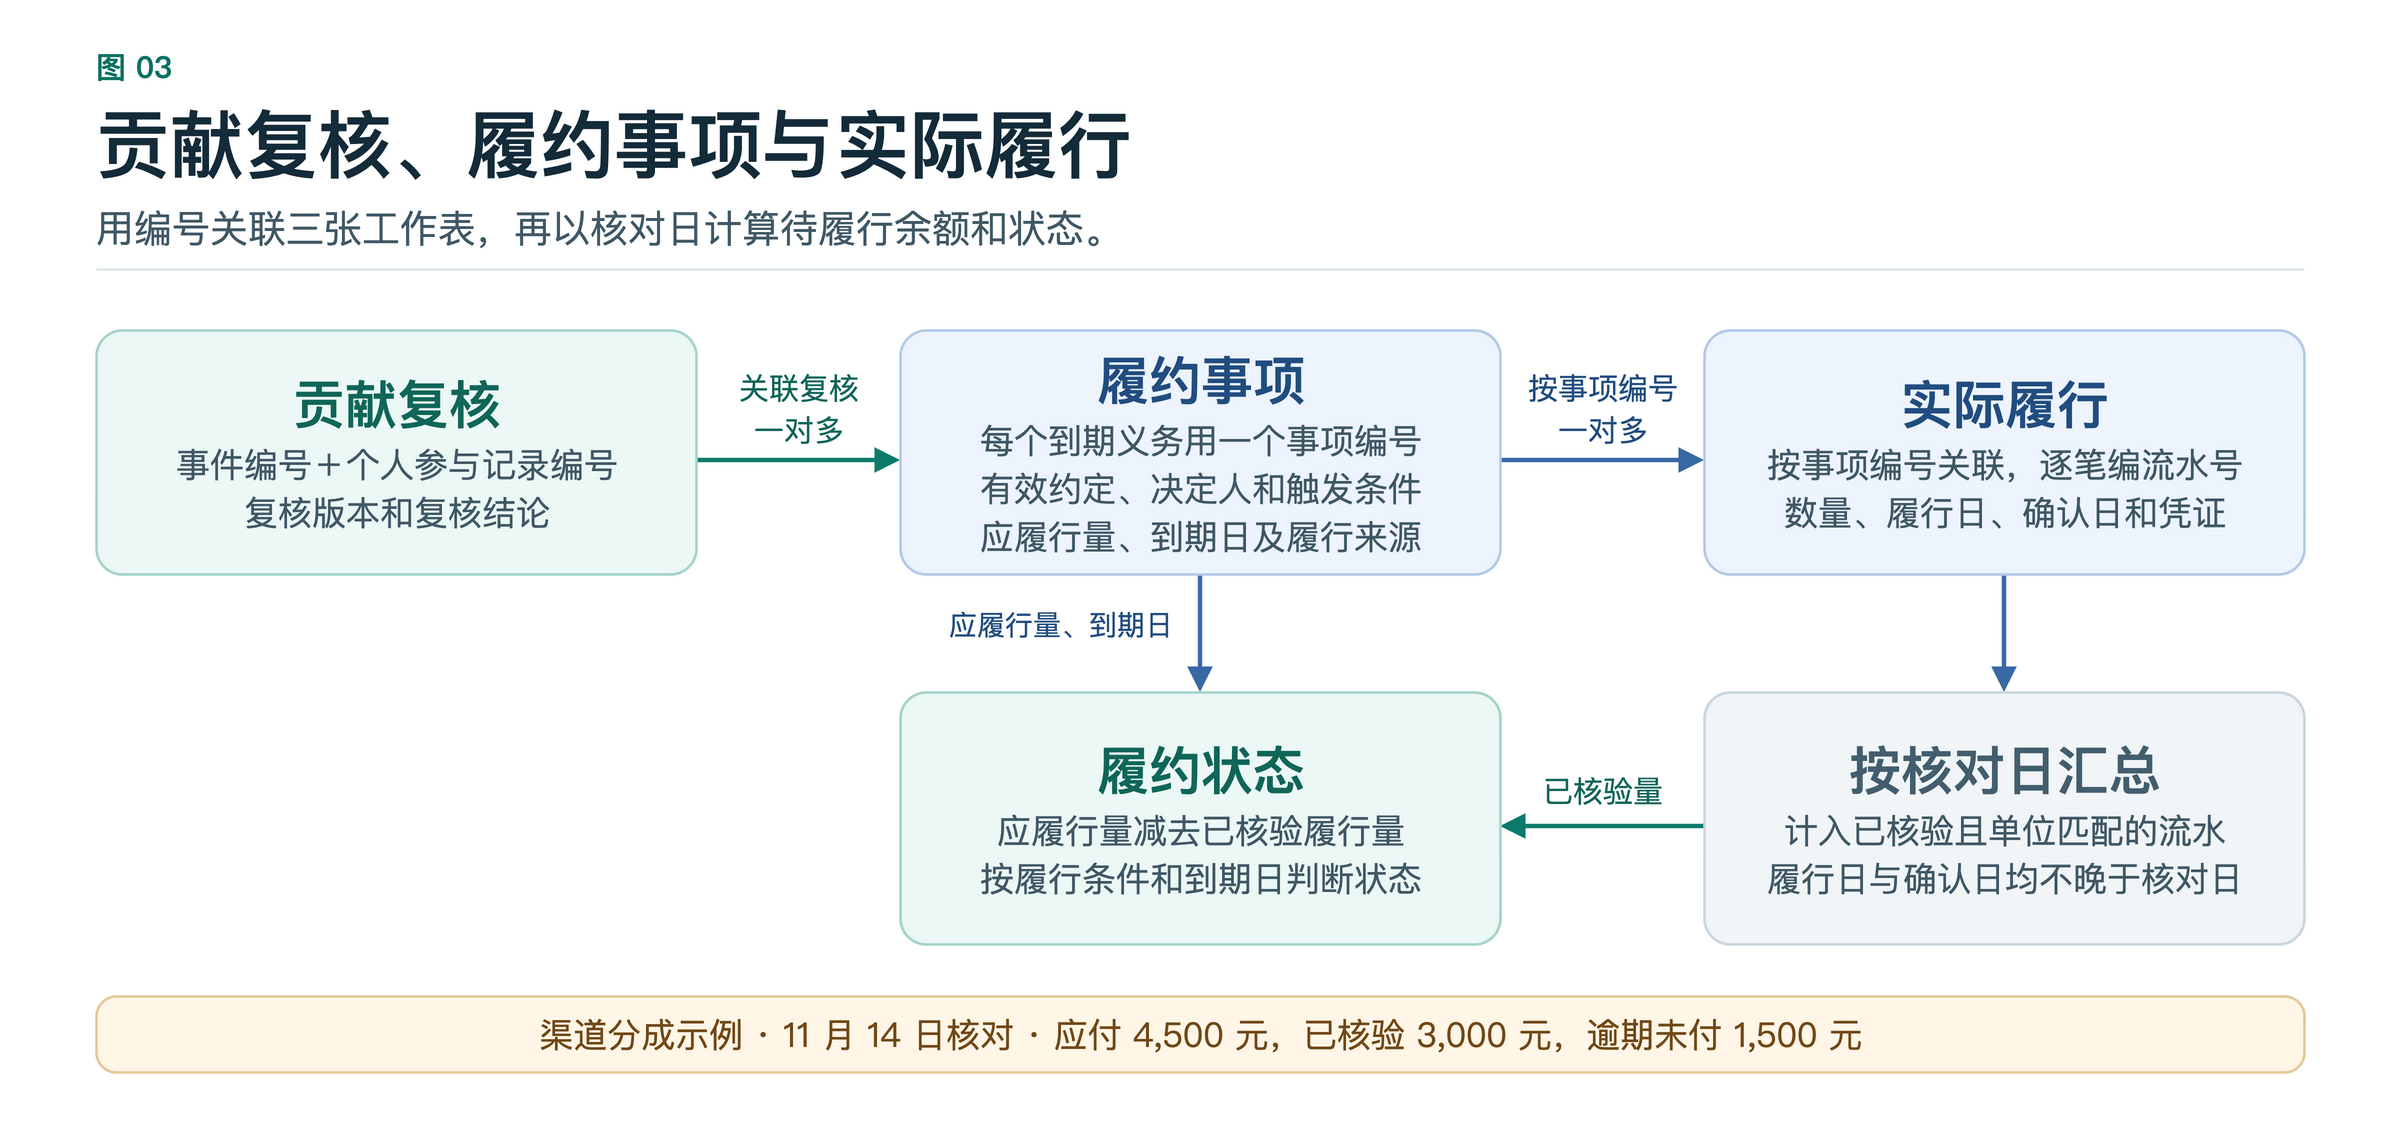
- Figure 3. One contribution review may link to several obligations, each with several actual fulfillment entries. As of the review date, supporting records show RMB 4,500 due, RMB 3,000 verified as paid, and RMB 1,500 overdue.
- Download the Draw.io source (five pages, Chinese) ↓
This is a readable, citable knowledge resource, not an installed Skill. When using it with AI, retain its sources and limits and review the output.
CC BY-NC-ND 4.0 · Applies to original text unless otherwise stated; excludes third-party materials. Downloading or machine reading does not extend the existing license or separately authorize derivatives, commercial use or model training.
WISERUNION Think Tank · Tool V0.1 · November 14, 2026
Download the editable Excel tracking sheet (Chinese) ↓
The contribution has been reviewed and the parties have agreed to share proceeds. On the review date, which obligations are due? Which payments were actually made, and where is the evidence?
I start with the original contribution record, then follow it to the decision on the right, the relevant terms, and the due date. Project leads, people authorized to decide rights, and finance or delivery leads can all use the same record to check how much was fulfilled.
Link contribution review to fulfillment

View full-size figure ↗Download the Draw.io source (five pages, Chinese) ↓
- Reference a reviewed contribution. In Contribution Review, carry forward the event ID, individual participation record ID, evidence location, review result, and reasons from the existing sheet. Add the review version. Enter both IDs and the review version in the corresponding row of Obligations. One joint outcome may relate to multiple participants and rights. Refer to the existing records of joint participation and overlaps when checking them. Contribution Records and Review Worksheet
- Record rights and obligations. In Obligations, assign each obligation coming due its own ID. If settlement occurs in installments, use one row per installment. Record the right holder, obligor, applicable document and clause, who made the decision, where their authority comes from, and how to verify the fulfillment conditions. Then add the source of funds or delivery resources, due date, quantity, and unit. For a payment, identify the relevant project funds or budget. For goods, services, or permissions, specify what will be delivered and who is responsible.
- Verify each act of fulfillment. In Actual Fulfillment, enter the obligation ID, a unique ID for each entry, fulfillment date, quantity and unit, evidence location, verifier, and verification status and date. Use proof of receipt for payments, sign-off and acceptance records for goods or services, and authorization and access activation records for governance permissions. Use the same unit as the obligation. Record each installment or delivery separately.
- Review status as of a specific date. Enter the review date in cell B3 of Obligations. Check whether each item is due, its fulfillment status, the verified amount, the balance, and whether it was fulfilled on time. An entry counts only after verification and if both fulfillment and verification took place on or before the review date. If there is an indication of fulfillment but evidence is incomplete, log the entry as pending verification and follow up. An item shows as Due Today on its due date and can become overdue the next day. Amounts and quantities are calculated to two decimal places.
The workbook provides 100 rows each for Obligations and Contribution Review, and 300 for Actual Fulfillment. For an actual project, clear the inputs marked Example and retain the columns with blue formula cells.
Channel partnership example
Use the fictional channel partnership from the model article. Set the review date to November 14, 2026, and check where the three commitments stand. How Stakeholders Form Long-Term Capital Relationships
| Obligation | Terms and evidence | As of the review date |
|---|---|---|
| Current channel revenue share | Eligible net receipts of RMB 90,000 at the agreed 5% rate produce RMB 4,500 payable. It was due November 12. Receipt evidence verifies a payment of RMB 3,000. | Partially fulfilled, with RMB 1,500 overdue. |
| Revenue share from another order | Eligible customer receipts trigger payment. The order has been signed and payment has yet to arrive. | The condition is pending. Calculate the amount and date due once funds arrive. |
| Activation of governance access | Activate one permission to review channel attribution as agreed. Both authorization and activation records can be verified. | The obligation to grant access is fulfilled. Record any actual participation separately using meeting or case records. |
If a dispute arises, return to the relevant item and record the objection, evidence, and review result. When terms or a decision change, record both versions, who decided, when the change takes effect, and which items it affects. Recheck fulfillment to date before updating the deadline and obligation under the effective decision. To retain a record for a given date, save a copy of the workbook before making changes.