From ecosystem relationships to governance in practice
Many parties create a company's value together. Resources and technology enable supply; labor and management organize delivery; customers' real needs test the product; and capital supports development while bearing agreed risks. Once these relationships are understood, further questions follow: How is each party's contribution confirmed? What establishes its rights and entitlements? Who decides a particular matter? How do execution results inform improvements to operations and rules?
The four-ecology governance model connects participation, value creation and governance around these questions. It builds on Stakeholder Ecosystem Digital Governance: Four Ecosystems, Six Value Systems, and Three Layers, adding detail at the level of contribution events and governance matters.
This edition upgrades the V1 governance map to V1.1, adding value flows across ecosystems, authority for individual matters, the basis of entitlements, and feedback for correction. It supports organizational observation and discussion of institutional design. Specific arrangements must be confirmed for the actual entity, rules and business.
1. Four ecosystems identify who participates and through which relationship
| Ecosystem | Main relationship | Contributions to confirm |
|---|---|---|
| Resource | Production: resources and collaboration | Resources, technology, knowledge, professional outputs and contractual delivery |
| Customer | Consumption: trust and co-creation | Genuine consumption, effective use, feedback, co-creation and verified referrals |
| Operations and management | Labor and organizational relations: delivery and organization | Labor, R&D, management, professional services and continued fulfillment of responsibilities |
| Capital | Investment: funds and risk | Actual funding, clearly defined risk-bearing and agreed capital services |
These ecosystems classify relationships. A person can be a supplier, employee, customer and investor at the same time; contributions, responsibilities and entitlements are recorded separately. One output may relate to several collaborative tasks, but counting it more than once for incentives requires an explicit basis in the rules.
Each ecosystem is examined through five dimensions: participants, valid contributions, verification and responsibility, rights and conditions, and governance matters. The diagram sets out this structure; the original Chinese interactive map also provides suggested evidence and responsibility arrangements.
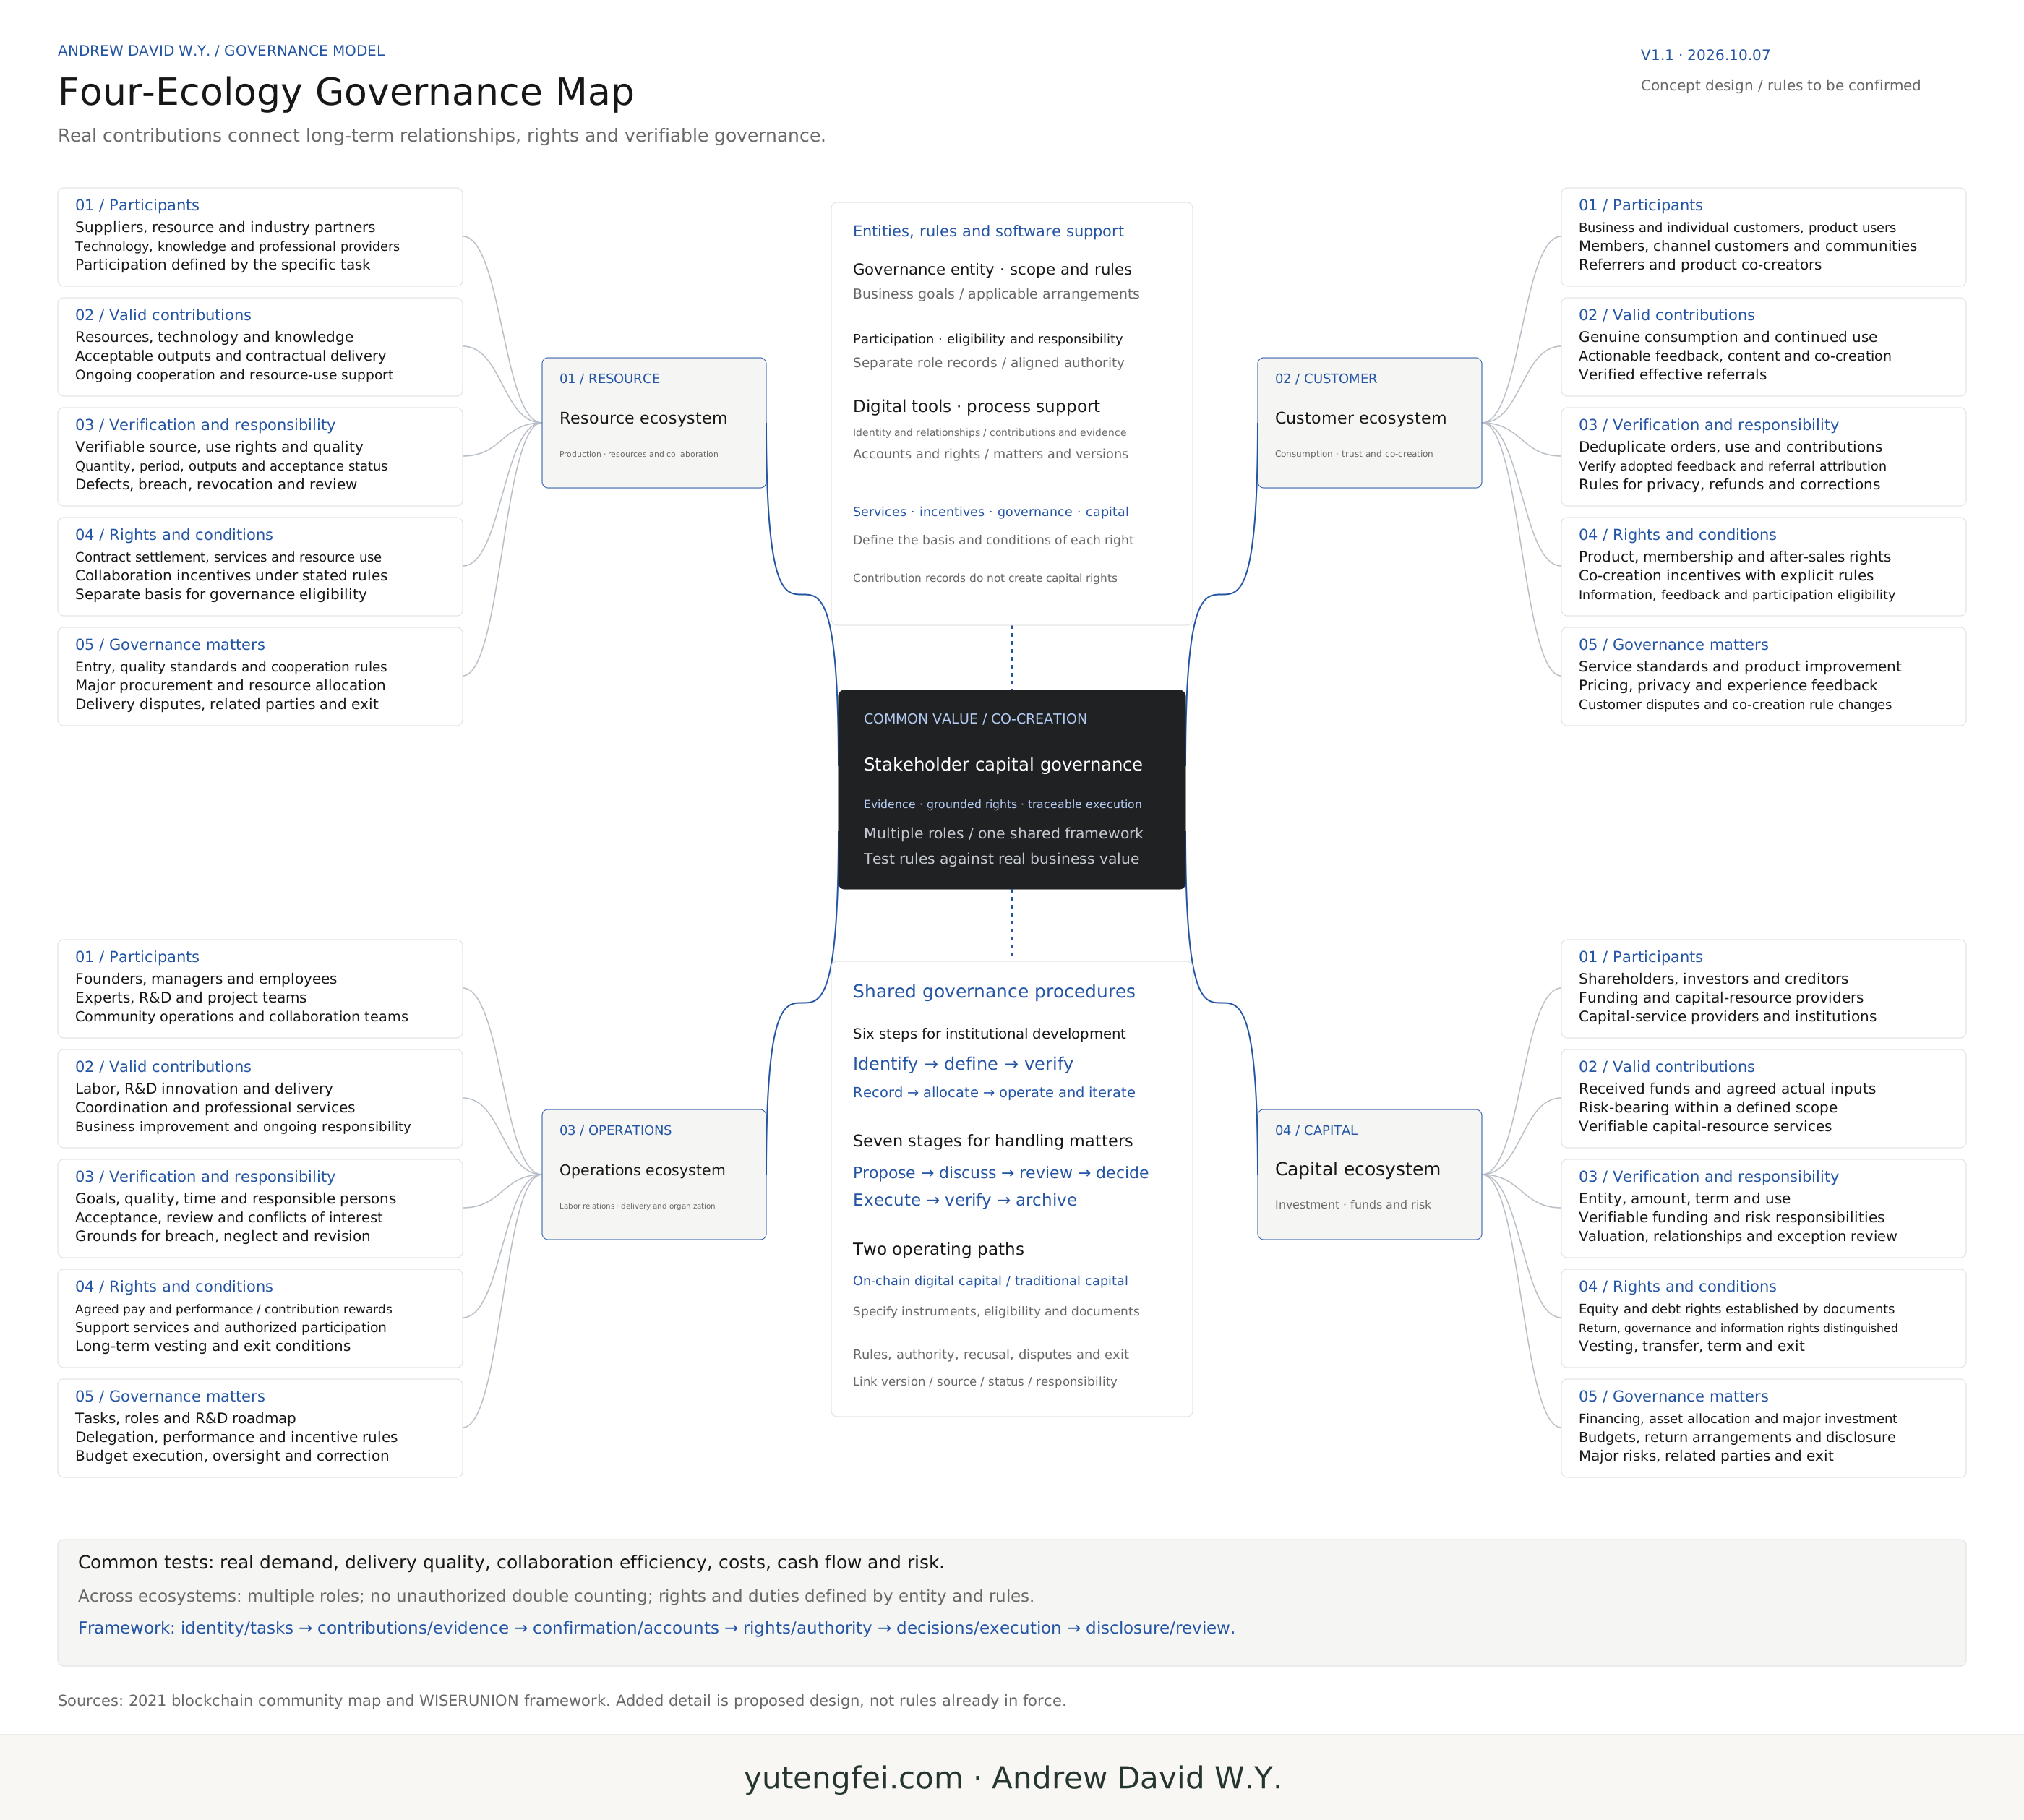
Open the interactive map (Chinese original): zoom, pan, focus and node details ↗
2. How value flows between ecosystems
The model's review path is: shared goals and constraints → resource and capital inputs → organized collaboration and acceptance → customer transactions and fulfillment → cost and return accounting → allocation and reinvestment under the rules.
This path does not guarantee that inputs will generate returns. Customer needs, actual use, differences in fulfillment, cash receipts and changes in risk may all require adjustments to products, tasks, budgets, incentives and rules.
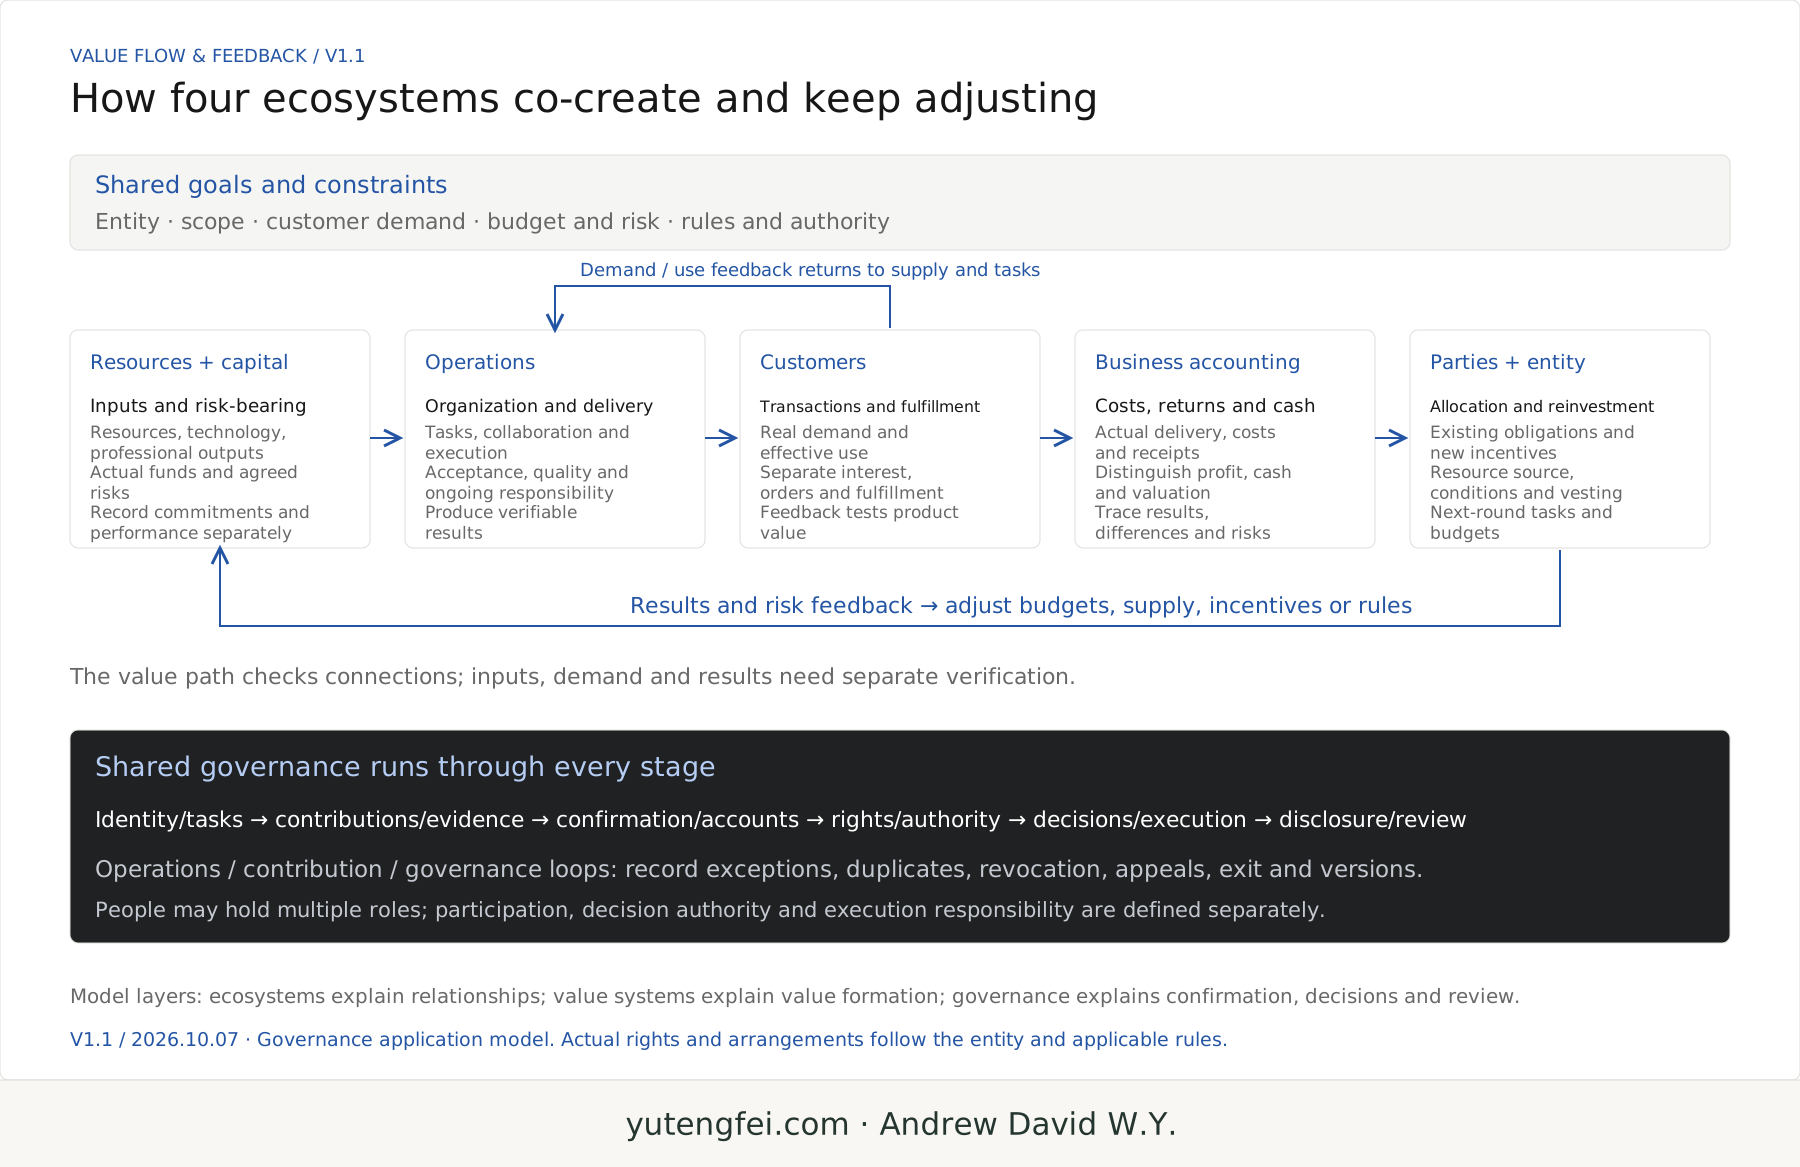
The four ecosystems, six value systems and governance process use different levels of observation. The core value system aligns goals; the production system enables supply; the sales system connects customers; the returns system accounts for results; the amplification system examines reinvestment and expansion; and the operations and management system runs through collaboration and rules. Their relationships overlap; there is no one-to-one mapping between the four ecosystems and these systems.
3. Confirm contributions, then establish the basis of entitlements
A contribution must at least identify who participated and in which role, the task completed, the output produced, where the evidence is held, who confirms it, the applicable rule version and its current status.
Once a contribution is confirmed, its contractual relationship, eligibility, responsibilities, risks and entitlement conditions must be stated. A long-term account records contributions and their changes, while linking each type of service, incentive, governance and capital entitlement to its own basis.
Existing obligations—such as supplier payments, compensation and capital contracts—are listed separately from additional co-creation incentives. New arrangements must identify their resource source, accounting scope, budget or actual available funds, and vesting, adjustment and exit conditions. Revenue, profit, cash, valuation gains and contribution records have distinct meanings and cannot substitute for one another.
Governance eligibility does not automatically confer equity or investment returns. A contribution record does not grant authority over every matter. This model prescribes no universal contribution score, equity-conversion formula, allocation ratio or investment return.
4. Define decision authority for each matter
| Stage | Questions to clarify |
|---|---|
| Proposal and participation | Who may initiate a matter, submit evidence or join discussion? |
| Review and decision | Who reviews it, who makes the final decision, and what is the source and limit of their authority? |
| Execution | Who implements it, with which resources, deadline and acceptance conditions? |
| Verification and oversight | Who checks results and handles objections, and how are conflicts of interest managed through recusal? |
Eligibility to participate and discuss, decision authority, execution responsibilities and oversight powers are assigned separately. A particular matter may use consultation, delegated decisions or voting, with its procedure grounded in the applicable rules.
Institutional development follows six steps: identify, define, verify, establish records, allocate, and operate and iterate. Matters follow seven stages: propose, discuss, review, decide, execute, verify and archive. The former establishes rules; the latter records decisions and execution under them.
5. Test the model through three feedback loops
- Operations loop: demand, supply and delivery, customer fulfillment, quality and cash results feed back into operational adjustments.
- Contribution loop: tasks, output evidence, confirmation, entitlement arrangements, and verification or revision retain a traceable history.
- Governance loop: proposals, review and decisions, execution and verification lead to corrections, rule revisions or new proposals.
Exceptions, duplicate records, revocation, appeals, breach, exit and major risks require named responsible roles and clear handling statuses. Rule revisions explain how old and new versions connect; historical records retain their sources and changes. Operational review observes real demand, delivery, collaboration efficiency, costs, cash flow and risk.
6. Applying it to a gold mineral resource project
Research and implementation of a gold mineral resource project provide a collaboration example. The responsible entity first defines research goals, budget and authority. Resource partners submit mineral-resource information, conditions of use, testing and technical materials. The operations team develops research and engineering plans. Customer relationships verify real demand, recording expressions of interest separately from orders. Capital arrangements are reviewed against actual documents, with commitments, received funds and uses confirmed separately.
Information gaps, testing discrepancies, cost changes or insufficient demand send the relevant assumptions back to research and review. Only actual delivery, fulfillment, costs and cash receipts enter the corresponding accounts. Existing obligations, applicable incentives and verification are then handled under contracts and rules.
The example explains how to use the model; it does not establish that a specific project has been verified, invested in or generated returns. Company matters and project matters must each specify their applicable rules and decision authority.
7. Entities make decisions; software supports the process
The model can serve a particular company or project. Before implementation, define goals, the governance entity, business scope, relationships, rules and authority, then select digital tools. On-chain governance of digital capital and traditional capital governance can use the same governance framework, while separately specifying their instruments, eligibility, documents and execution methods.
Wiserunion is Company No. 0 and the first enterprise to apply NST. Wiser Asset is an independent company serving as an asset and governance platform and a provider of software services. NST supports identity, contribution, account, matter and version processes; actual capabilities depend on the product's released scope. Wiserunion's rules do not automatically govern Wiser Asset's investment, financing or project matters, and software records do not replace decisions by the responsible entity.
Model version and supporting materials
V1.1 was revised on 7 October 2026. It retains V1's four-ecosystem relationship structure and adds value collaboration, matter-level authority, the basis of entitlements, feedback and an application example. Practice still needs to establish contribution standards, authority, entitlement conditions, dispute handling, exit, disclosure scope and indicator observation periods.
- Interactive HTML (Chinese original)
- Governance structure SVG
- Value collaboration and feedback SVG
- Article Markdown
- Complete model Markdown (Chinese original)
- Model upgrade notes (Chinese original)
- Original V1 archive (Chinese)
Further reading: Four Ecosystems, Six Value Systems, and Three Layers; WISERUNION governance practice.